A financial question rarely exists by itself. A couple planning a wedding may also be combining debt, benefits, insurance, and long-term goals. New parents may be thinking about childcare and college tuition planning while realizing they need life insurance, updated beneficiaries, and an estate plan. Years later, the same family may be balancing college costs, retirement savings, aging parents, and a legacy for the next generation.
At Feliciano Financial, holistic financial planning begins with the whole picture, family financial planning. The goal is not to treat cash flow, investments, taxes, insurance, retirement, healthcare, and estate planning as separate assignments. The goal is to understand how those areas affect one another, then organize them into a coordinated strategy through The Feliciano Financial Blueprint™.
Financial planning is personal because family life is always changing
People do not move through life in one standard order. Someone may marry in their twenties, become a caregiver in their thirties, start a second family in their forties, or lose a spouse in retirement.
A household may include children from prior relationships, a sibling with special needs, or parents whose health and finances suddenly require attention. Ask yourself:
- Who depends on you?
- Whose decisions affect your plan?
- What responsibilities are changing?
- What needs protection now, and what should be prepared for next?
Those questions create context. Context is what turns a collection of accounts and documents into an actual financial plan.
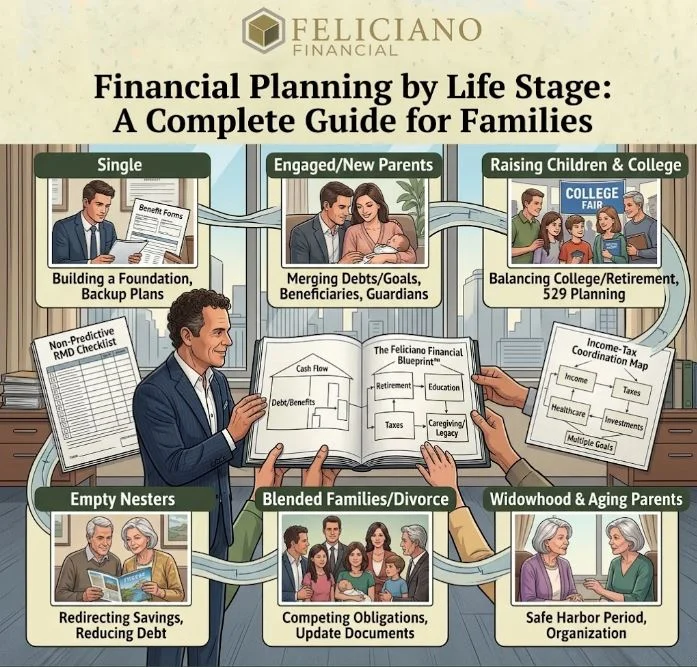
Single: Building a foundation that belongs to you
Being single does not mean financial planning is simple or unnecessary. It often means you are the primary person responsible for your income, emergency reserves, healthcare decisions, long-term savings, and future security. Planning may begin with cash flow, debt, workplace benefits, retirement contributions, insurance needs, and beneficiary designations. It should also consider who could act for you if you became incapacitated and where your assets should go if you died. The objective is independence with a backup plan, not isolation.
Engaged or Newly Married: Joining lives without losing clarity
Marriage brings together more than two people. It can combine income, debts, accounts, employee benefits, tax decisions, property, family expectations, and different attitudes about money.
A productive planning conversation establishes what will be shared, what may remain separate, how bills and savings will be managed, and how near and long-term goals will be prioritized. Beneficiaries, insurance coverage, emergency reserves, retirement plans, wills, trusts, and powers of attorney may all need review. If either person owns a business, there is business owners financial planning, or has children from a prior relationship, expects an inheritance, or holds significant separate property, legal and tax coordination becomes especially important.
The goal is not simply to merge accounts. It is to build a shared decision-making system with transparency, roles, and safeguards.
New Parents: Protecting the people who now depend on you
The arrival of a child changes the purpose of many financial decisions. Cash flow must absorb new expenses. Insurance has to reflect the income and caregiving each parent provides. Beneficiary choices and estate documents must support the child, and parents may need to nominate guardians and establish an appropriate structure for inherited assets.
Education savings can matter, but it should be considered alongside emergency reserves, debt management, retirement contributions, and adequate protection. Holistic planning helps parents avoid solving one visible goal, such as college, while leaving a more urgent risk unaddressed.
Raising Children and Paying for College: Balancing today with tomorrow
During the child-raising years, families often face several goals at once: housing, activities, education, transportation, healthcare, family experiences, and retirement. The challenge is not finding a goal worth funding. It is deciding how much each goal can receive without weakening the household’s overall stability.
College planning may include a 529 plan, scholarships, grants, cash flow, student loans, and other resources. Yet the college decision also affects retirement savings, taxes, investments, and the financial expectations parents set with their children. A coordinated plan compares the tradeoffs before commitments are made.
Empty Nesters: Redirecting resources with intention
When children become independent, a household’s spending and priorities may shift. This can create an opportunity to increase retirement savings, reduce debt, reassess housing, update insurance, revisit investment risk, and clarify legacy goals. It is also a useful time to discuss how much ongoing support adult children may receive and whether that support affects the parents’ retirement security. The empty-nest transition is not merely the end of one stage; it is a planning window for the next one.
Blended Families, Divorce, and Remarriage: Coordinating competing obligations
Blended families often have responsibilities and loyalties that cannot be handled with default forms. A beneficiary designation may override a will. Leaving everything outright to a surviving spouse may not guarantee that children from an earlier relationship ultimately inherit. Property ownership, support obligations, trusts, insurance, and retirement accounts must be reviewed together with qualified legal and tax professionals.
Divorce can require rebuilding cash flow, separating property, updating coverage, revising beneficiaries, evaluating retirement assets, and replacing estate documents. Remarriage creates another coordination point. The objective is to translate family intentions into financial and legal structures that work together.
Widowhood: Creating space before making permanent decisions
The death of a spouse can create grief, paperwork, deadlines, and pressure at the same time. The first planning priority is often to organize: identify immediate cash needs, secure key documents, understand benefits and account ownership, and separate urgent actions from choices that can wait.
Over time, the surviving spouse may need to rebuild an income plan, reassess investments and taxes, update beneficiaries and estate documents, review insurance, and decide whether housing or lifestyle changes make sense. Holistic guidance can help establish an order of operations so that irreversible decisions are not made before the full picture is understood.
Caregiving, Special needs, and the Sandwich Generation
Family financial planning often expands beyond a spouse and children. A person may be helping an aging parent, managing money after a relative’s stroke, supporting a sibling with a disability, or caring for children and parents simultaneously. These situations connect healthcare, legal authority, housing, public benefits, insurance, taxes, cash flow, and estate planning. Families may need to clarify who can make decisions, who controls accounts, what care costs, how responsibilities will be shared, and how the caregiver’s own retirement and wellbeing will be protected.
For a person with special needs, planning may also involve benefit eligibility, a special needs trust, an ABLE account, appropriate beneficiary language, future caregivers, and a written letter of intent. Attorneys and tax professionals should be involved where legal documents or tax consequences are at issue. The financial plan serves as the coordination framework that keeps these moving parts aligned.
The Holistic Financial Questions for Every Family
Although every family is different, the planning process repeatedly returns to a connected set of questions:
- What has changed in the household, and what decisions now have a deadline?
- How will income, spending, debt, and emergency reserves support the family’s current responsibilities?
- Are savings and investments aligned with the household’s time horizons and tolerance for risk?
- Could death, disability, illness, or long-term care disrupt the plan?
- Do insurance coverage and employee benefits match the people who depend on the household?
- Are beneficiaries, account ownership, wills, trusts, and powers of attorney coordinated?
- How could today’s decision affect taxes, retirement readiness, healthcare costs, or the family’s legacy?
- Which decisions require coordination with an attorney, CPA, insurance professional, benefits specialist, or other professional?
The point is not to make every family solve every issue at once. It is to identify the most important next decisions while making sure a solution in one area does not create a new problem somewhere else.
A strong family financial plan should be able to change as the family changes. It should support a single person establishing independence, a couple creating a shared future, parents protecting children, a caregiver managing new responsibilities, and older generations preparing for retirement and legacy.
Wherever you are in your family story, Feliciano Financial can help you see the connections, understand the choices, and determine the next step.
Call or send us a message online to explore educational resources or begin a conversation about your family’s financial picture.
When you are ready: Schedule your discovery call at 903-533-8585 to begin YOUR Feliciano Financial Blueprint.
Still want to learn more? Check out: Feliciano Financial on YouTube – Feliciano Financial Financial Planners & Advisors Glossary
- Wealth Management Services
- Retirement Planning Services
- Family Financial Planning
- Asset Protection
- Cash Flow Management
- Charitable Tax Deductions
- College Planning
- Investment Planning
- Private Family Foundations
- Professional Specialties
- Tax Planning
- Wealth Planning
- Business Owner Financial Planning
This content is for educational purposes only and does not constitute legal advice. Please consult a qualified attorney for legal recommendations. Tax and legal services are not offered by Integrity Alliance, LLC. Securities and investment advisory services offered through Integrity Alliance, LLC, Member SIPC. Integrity Wealth is a marketing name for Integrity Alliance, LLC. Feliciano Financial is not affiliated with Integrity Wealth.
