For a business owner, your company is rarely just a place of work.
It may provide your household’s income, health insurance, retirement savings, family employment, tax opportunities, and sense of purpose. It may also be your largest asset, greatest financial concentration, most significant liability exposure, and primary plan for retirement.
That is why business financial planning cannot stop with the company’s bank account and personal financial planning cannot ignore the business.
A business can look successful while leaving the owner financially exposed. Revenue may be growing, but cash may be tied up in receivables, inventory, payroll, equipment, or expansion. The company may be profitable, but the owner may have limited personal savings outside the business. Employees may receive benefits, while the owner has no disability or continuity plan. The business may be worth millions on paper, but there may be no ready buyer, successor, current valuation, or funded buy-sell agreement.
These gaps often remain hidden because each professional sees only one part of the picture. The CPA focuses on tax filings. The attorney prepares agreements. The banker evaluates credit. The benefits provider manages the plan. The insurance professional addresses coverage. The investment advisor manages personal accounts. All of that work may be valuable, but without coordination, the owner may still lack one clear strategy.
Holistic financial planning for business owners brings those moving parts into the same conversation.
Starting and Establishing the Business
At the beginning, the most important questions often involve startup capital, entity structure, business and personal account separation, bookkeeping, taxes, insurance, owner compensation, and household reserves. The objective is not merely to open the doors. It is to launch without allowing the business to consume every personal resource or transfer unnecessary risk to the family.
Growing and Hiring
Growth introduces working-capital demands, debt, payroll, worker classification, new locations, equipment, and management responsibility. Hiring creates decisions about compensation, health benefits, retirement plans, and the full cost of employees. Profit and cash flow must be understood separately because a growing business can be profitable and still run short of cash.
Building the Team and Protecting Continuity
As the company becomes more valuable, the owner must consider key-person dependency, disability, life insurance, operating continuity, management depth, cybersecurity, property and liability risk, partner agreements, and what happens if an owner or critical employee becomes unavailable, known as “key-man insurance“.
Creating Owner and Employee Benefits Strategies
A retirement plan can help the owner build personal retirement assets while supporting employee recruiting and retention. But plan design also involves contribution goals, workforce demographics, cash-flow consistency, administration, fees, and fiduciary responsibilities. The right plan is not simply the one with the highest contribution limit; it is the one that fits the company and can be operated responsibly.
A mature business should become more than a demanding job for its owner. Reliable financial records, diversified customers, recurring revenue, documented systems, strong management, clean agreements, and reduced owner dependence can help create value that another person can actually finance, operate, and transfer.
Preparing for Business Succession, Sale, or Retirement
An owner may want to transfer the company to family, sell to employees, bring in management, or pursue an outside buyer. Each path raises different questions about valuation, taxes, financing, control, family fairness, estate planning, employee continuity, and the income the owner will need after leaving.
The exit price alone does not create a retirement plan. Owners must understand net proceeds after taxes, debt, fees, escrows, earnouts, and retained obligations and then determine how those proceeds will support lifetime income, healthcare, investments, family goals, philanthropy, and legacy.
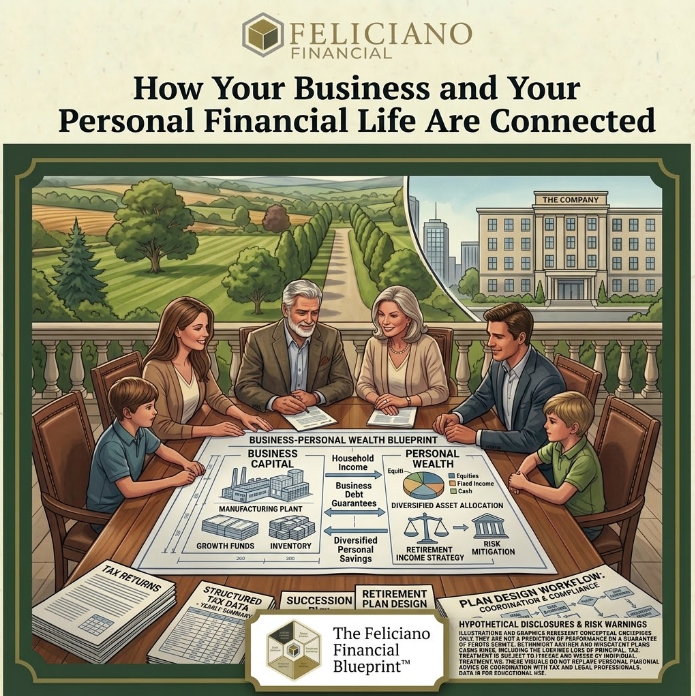
Business Capital vs. Personal Wealth
Many owners reinvest nearly everything in the company. That commitment may drive growth, but it can also create concentration. The same asset may provide the owner’s income, net worth, collateral, retirement expectations, and family legacy. If the business is disrupted or cannot be sold on the expected terms, several goals can be affected at once.
Holistic financial planning for business owners asks how much capital the business truly needs and how the owner can gradually build financial resources outside it. That may include personal emergency reserves, retirement plans, diversified investments, insurance, debt reduction, real estate decisions, and an exit strategy based on realistic value rather than hope.
The Feliciano Financial Blueprint™ for Business Owners
1. Organize
Bring together business and personal balance sheets, cash flows, tax returns, debts, benefits, insurance, ownership documents, retirement plans, estate documents, valuations, and agreements. Identify who makes decisions and which professionals are already involved.
2. Simplify
Separate operating needs from owner goals. Distinguish urgent compliance or liquidity decisions from longer-term planning. Identify which decisions belong to the business, which belong to the household, and where they overlap.
3. Clarify
Understand the tradeoffs among reinvestment, owner distributions, debt, taxes, employee benefits, retirement savings, insurance, diversification, valuation, control, succession, and legacy. Clarity means knowing what a decision solves and what it may change elsewhere.
4. Coordinate
Help the attorney, CPA, banker, benefits providers, insurance specialists, valuation professionals, and financial planning team work from the same facts and intended outcome. The objective is not to replace specialized advice. It is to help the specialties work together.
What holistic business-owner planning should connect
- Business and household cash flow
- Owner compensation, distributions, and tax reserves
- Debt, liquidity, and personal guarantees
- Employee health, insurance, and retirement benefits
- Owner and key-person life and disability protection
- Retirement-plan design and fiduciary responsibilities
- Business insurance and asset protection
- Partner, shareholder, and buy-sell agreements
- Business valuation and transferable-value drivers
- Succession, sale, and exit planning
- Personal retirement income and investment diversification
- Estate planning, family dynamics, and legacy intentions
Not every owner needs every strategy today. The purpose of the process is to identify what matters most at the current stage while keeping the next stage visible.
Common Business Financial Planning Mistakes
- Using the business bank balance as the only measure of financial health.
- Mixing personal and business finances or allowing recordkeeping to fall behind.
- Reinvesting everything while building little retirement or liquidity outside the company.
- Offering benefits or incentive plans without first defining the business objective and sustainable cost.
- Assuming a generic valuation multiple is enough for succession, insurance, or retirement planning.
- Relying on an outdated or unfunded buy-sell agreement.
- Waiting until illness, conflict, burnout, or a buyer’s offer forces the succession decision.
- Accepting sale terms before modeling taxes and the owner’s life after closing.
- Receiving separate recommendations from multiple professionals without one coordinated plan.
Questions Every Business Owner Should Ask
- How dependent is my household on the company?
- How dependent is the company on me or one key employee?
- Do I know the true cash needs of the business and the family?
- Am I building retirement assets and liquidity outside the company?
- Are employee benefits aligned with recruiting, retention, cash flow, and owner goals?
- Are my business and personal insurance plans coordinated?
- What is the business realistically worth and what makes that value transferable?
- What happens if I die, become disabled, disagree with a partner, or need to leave earlier than expected?
- Who could own and operate the business next?
- How much after-tax income will I need when the company no longer provides it?
- Are my attorneys, CPA, benefits, insurance, valuation, and financial professionals working toward the same outcome?
YOUR business is important, but it is not the final outcome. The outcome is what the business allows the owner, family, employees, customers, and community to build, protect, and carry forward.
Feliciano Financial helps business owners organize the company and household, simplify the decisions, clarify the tradeoffs, and coordinate the professionals involved. That creates a clearer path from today’s business stage to personal financial confidence, retirement readiness, succession, and legacy.
When you are ready:
Contact US to schedule your discovery call at 903-533-8585 to begin YOUR Feliciano Financial Blueprint.
Still want to learn more? Check out:
- Wealth Management Services
- Retirement Planning Services
- Family Financial Planning
- Asset Protection
- Cash Flow Management
- Charitable Tax Deductions
- College Planning
- Investment Planning
- Private Family Foundations
- Professional Specialties
- Tax Planning
- Wealth Planning
- Business Owner Financial Planning
This content is for educational purposes only and does not constitute legal advice. Please consult a qualified attorney for legal recommendations. Tax and legal services are not offered by Integrity Alliance, LLC. Securities and investment advisory services offered through Integrity Alliance, LLC, Member SIPC. Integrity Wealth is a marketing name for Integrity Alliance, LLC. Feliciano Financial Group is not affiliated with Integrity Wealth.
